Why Independence Still Matters in Real Estate Insurance
The insurance broking market has changed considerably over the past decade. Consolidation has reshaped much of the sector, and a growing share of the brokers and insurers that property owners deal with day to day are now owned by large corporate groups or private equity investors.
We have watched that shift happen from the outside, by choice. Against that backdrop, it's worth asking a simple question: what does it mean to work with an independent broker, and does it still matter?
For UK property owners, investors, developers and managing agents, the answer is yes, arguably more than ever.
What "Independent" Actually Means
The word "independent" is used loosely across financial services, so it's worth being precise. In insurance broking, genuine independence means three things:
- No ownership ties to a single insurer or group that could influence which products get recommended.
- No preferred partner arrangements that quietly narrow the range of insurers considered before advice is even given.
- A remuneration model that doesn't change depending on which insurer is used, so there's no financial incentive to steer a client toward one option over another.
A broker can call itself independent without meeting all three conditions. The distinction matters because each one, on its own, can subtly shape the advice a client receives, often in ways that aren't visible from the outside.
Why Consolidation Changes the PictureBroker and insurer consolidation isn't inherently a problem, and scale can bring real efficiencies. Many consolidated groups serve their clients well. But consolidation does tend to change the structure behind the advice, and it's worth understanding how.
Where a broker is part of a larger group, or operates within defined partner arrangements, the range of insurers considered can naturally be shaped by those existing relationships. This isn't unique to consolidated firms, but it becomes more structural at scale, simply because of how larger groups are typically organised. Ownership by private equity or other outside investors adds a further consideration. These firms typically plan to sell the business again within a set number of years, which can shape decisions differently than a business built for indefinite, long-term ownership.
None of this means advice from a consolidated broker is worse. It simply means that advice is shaped by a different set of structures and understanding those structures is part of making an informed choice.
Why Real Estate Specifically Needs Specialist KnowledgeWhile cyber insurance provides important financial protection, insurers increasingly expect businesses to demonstrate that they have taken practical steps to reduce their exposure to cyber threats.
Independence solves one part of the picture. The other is specialism.
Real estate risk is not generic commercial risk. A portfolio of managed residential blocks, a mixed-use development under construction, and a single-let commercial unit all carry meaningfully different exposures. Reinstatement valuation, occupancy risk, construction risk, tenant liability, service charge implications, and regulatory considerations like building and fire safety legislation all vary significantly by asset type and use.
A broker without deep, specific experience in property and real estate may still produce a policy, but the quality of the underlying risk advice, and the ability to spot where a standard policy doesn't quite fit a property's real circumstances, tends to reflect how much of the broker's day-to-day work is actually in this sector.
What Independence Delivers in PracticePut together, independence and specialism change what a client actually gets:
- Implementing strong cyber security controls
- Advice that reflects the property, not the panel and recommendations based on what a building and its use require, not on which insurers a broker has closest ties to
- Transparency on remuneration, so a client can be confident the advice they're given isn't influenced by which product earns the broker a bigger commission
- Continuity of relationship, since independent brokers are not subject to the same ownership changes, restructuring, or strategic pivots that can disrupt service at larger, consolidated firms
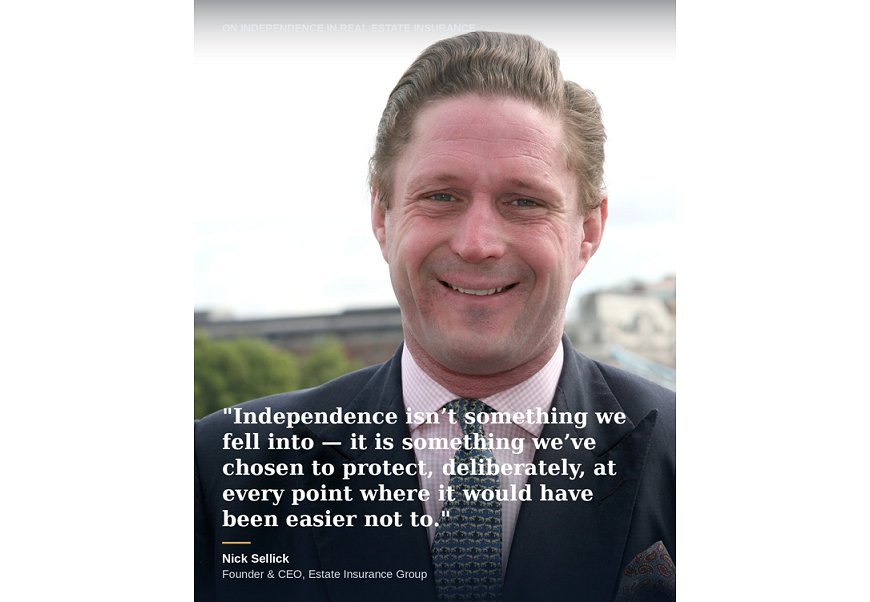
"Independence isn't something we fell into, it is something we've chosen to protect, deliberately, at every point where it would have been easier not to. It means every recommendation we make is built around a client's property, not around who we're owned by or who pays us the most. That's not a slogan for us. It's the reason this business still looks the way it did when it started." Nick Sellick CEO, Estate Insurance Group
A Sector-Wide Consideration, not a Sales PitchThis isn't a case against consolidated brokers, many of whom serve their clients well. It's a case for understanding what you're getting when you choose a broker, and for recognising that independence and specialism are not default features of the market, they're a deliberate choice, on both sides.
For property owners, investors, developers, managing agents and real estate advisers making decisions about who arranges their insurance, it's a fair question to ask directly: is this advice shaped by my property, or by someone else's commercial arrangement?
The Key PointIndependence in insurance broking isn't a marketing term, it's a structural feature that affects the advice a client receives, whether or not that influence is visible. Combined with genuine specialism in real estate, it means advice built around a property's actual risk profile, supported by a broker whose incentives are aligned with getting that advice right.
In a market shaped increasingly by consolidation and preferred partner arrangements, that combination is not just a point of difference. For many property owners, it's the reason to ask more questions before choosing who advises them.
Disclaimer: The information provided in this article is for general informational and educational purposes only and does not constitute formal finance, legal or regulated insurance advice. Insurance coverage is subject to specific policy terms, conditions and exclusions and underwrite appetites.


